
The self-managed board’s mid-year financial check-up
Written by: Christine Ponce
Published on: September 10, 2026
If your board handles finances, vendor contracts, and collections without a management company, you’re part of the 30% to 40% of community associations nationwide that are self-managed. That means you have no property manager, no outside accountant, but just volunteers who took on financial accountability. Because you won’t have the safeguards a management company normally provides, and the board has to be the one to catch anything that might be slipping, that’s why you need a mid-year financial check-up.
And when I say “Mid-year”, I don’t mean June 30th. What matters isn’t the specific month: it’s stopping at the six-month mark of your own fiscal year. But since most associations run a January-through-December year, that would turn out to be June 30th anyway. After six months in, you have enough data to spot a trend and still enough runway to act on it. For example, a budget overage caught in July is one focused correction. But if you find it in November, it becomes a post-mortem you carry into next year’s budget.
Also, a mid-year financial check-up isn’t the same as your monthly close. It asks a different question, not “did we record everything correctly,” but “at this rate, does our year end where we told homeowners it would?” If you know your trajectory by summer, you can start explaining a possible dues increase months before a formal notice lands. That said, I’ll walk you through the four areas of a self-managed board’s mid-year financial check-up: your budget-to-actual numbers, your reserve fund, your delinquencies, and your vendor contracts.
Start with your budget-to-actual report
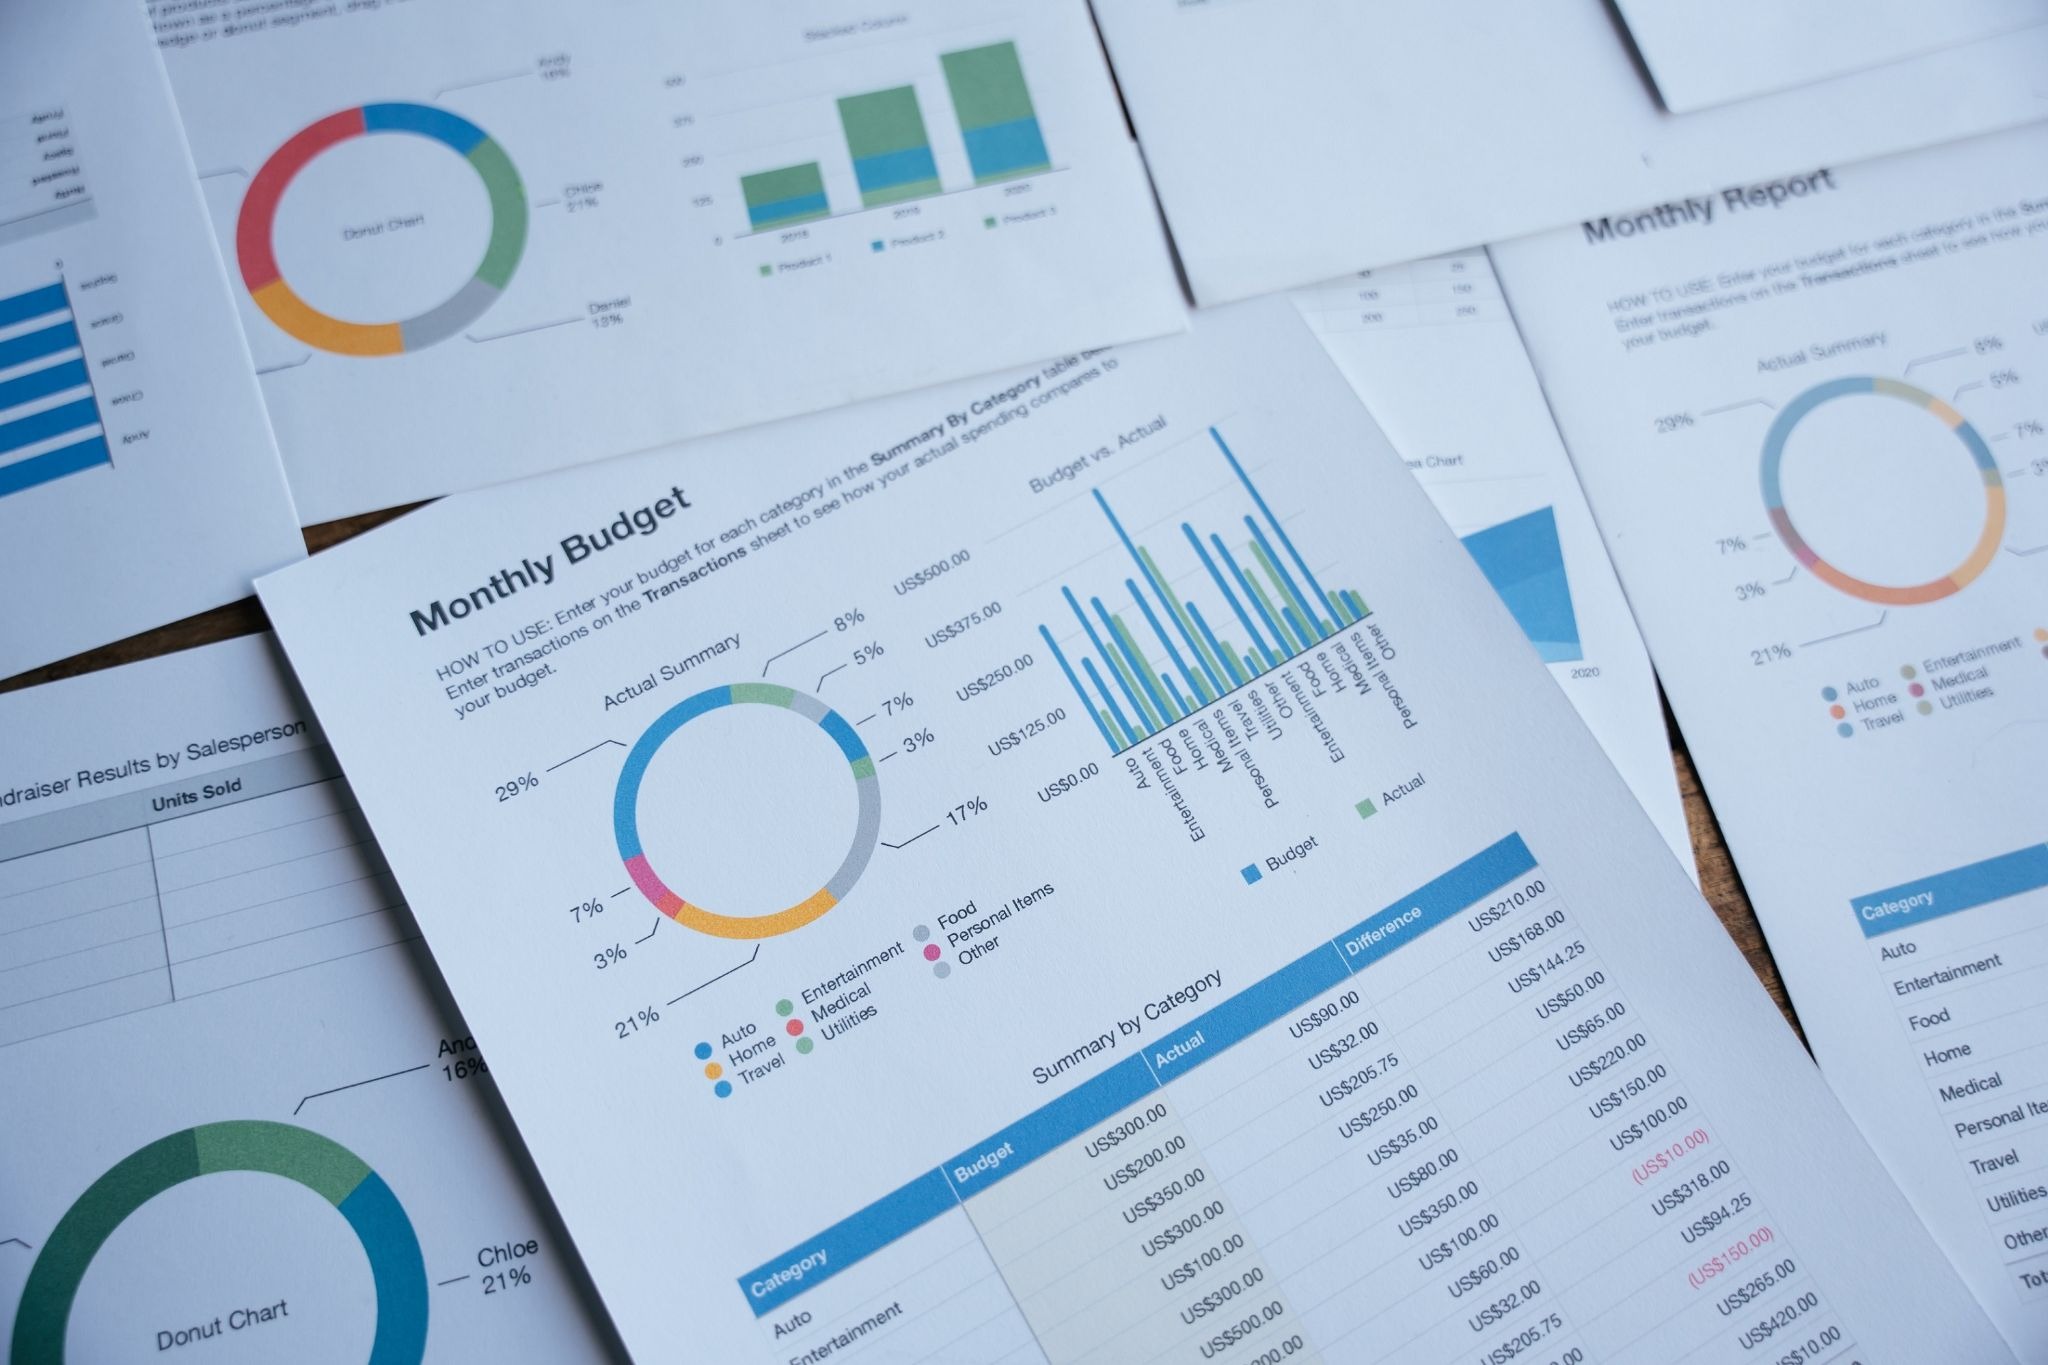
For most self-managed boards, this is the only financial control running. A budget-to-actual comparison lines up what you planned against what’s actually moved through your accounts. In a managed community, someone reviews this before the board sees it. In a self-managed one, that’s your treasurer, working in whatever hours are left after their daily job.
Doing this at mid-year, not just at year-end, is what gives it value. Manufacturing’s old 1-10-100 rule applies: catching a problem early costs roughly one unit of effort, catching it downstream costs about ten times as much, and catching it after it’s affected the result can cost a hundred times as much. For example, a landscaping line running hot in July is one conversation with your vendor. But the same overrun, undiscovered until December, turns out to be a dues increase that requires conversation with all owners.
How to run the comparison
Start with clean numbers pulled from your bank records and ledger. Calculate variance in both dollars and percentage, line by line, not just at the total. A landscaping line running 20% over and a utilities line running 20% under can net out to “on budget” while hiding a real problem underneath. And don’t assume 50% spent is the right benchmark at six months: some costs are front-loaded or seasonal, and your irrigation and water lines will almost certainly look over budget in a July review, which is normal for the season.
Set a variance threshold before you start, and stick to it. Most corporate finance teams flag anything 5 to 10% off budget or past a fixed dollar floor, whichever comes first, letting smaller deviations pass unexamined. I suggest you borrow the method. For anything that clears the threshold, ask: Is this a timing difference that resolves by December, or an overrun that will still be there at year-end? Check the income side too. If your budget assumes 100% of assessments collected on time and you’ve actually brought in 95%, that gap is a shortfall even if every expense line looks fine.
Whatever you decide, document it and check your notice requirements. Reallocating from an under-spent line, using a contingency line, amending the budget, or starting a special assessment conversation should all be recorded in the board minutes with the reasoning attached. Remember that many states require a minimum notice period before a dues increase above a certain threshold can take effect. So, catching things earlier gives you flexibility.
Check your reserve fund
This part of the review carries more urgency in 2026 than it did a year ago. On March 18, 2026, Fannie Mae and Freddie Mac published coordinated updates, Lender Letter LL-2026-03 and Bulletin 2026-C, that reshape how conventional lenders evaluate condo associations.
The changes raise the minimum reserve contribution from 10% to 15% of annual assessment income, effective for loan applications dated January 4, 2027 and beyond, and eliminate the streamlined “Limited Review” approval path for projects with more than 10 units, effective August 3, 2026, meaning nearly every conventional loan in your community now triggers a full review of your budget, reserve funding, insurance, and delinquency history.
If you’re a condo board doing this review now, January 2027 is one budget cycle away. An association that can’t hit 15% outright can still qualify by funding to the highest level its own reserve study recommends, but falling short on both puts your building’s warrantable status and your neighbors’ resale values at risk.
Even without the new lending rules, reserve underfunding is one of the most visible pain points in HOA communities. Nearly 10% of U.S. HOAs levied a special assessment in 2025, up from 7.8% in 2021, with a median bill of $1,100 (assessments tied to real structural repairs run far higher). Reserve specialists report that roughly 70% of the associations they review fall short of the 70% funding level the industry considers healthy.
How to review your reserve fund
Start with your reserve study: If your reserve study is more than three years old or has never been done, that’s the first thing to fix. A study inventories every major shared component (roofing, paving, HVAC, elevators, pool equipment), estimates remaining useful life, and prices out replacement at current costs. CAI standards call for a full on-site update at least every three years, with a lighter financial update in between.
- Calculate your percent funded: Your actual reserve balance divided by the fully funded balance that the study calculates. The benchmarks: 70 to 100% is healthy, below 30% is weak, with meaningful special assessment risk.
- Check your contribution rate against the new floor: Your annual reserve contribution divided by total operating expenses, against the 15% federal minimum for condos.
- Check what’s actually coming due: Pull the component schedule and look at anything with three years or less of remaining useful life. A healthy percent-funded number can still leave you exposed if the item due next is the roof rather than the pool deck furniture.
Review your delinquencies
Assessments fund your entire operating budget. Every dollar that doesn’t come in has to come from somewhere: reserves, borrowed future contributions, or eventually higher assessments on paying owners, which is the scenario a mid-year review is meant to catch early.
And this isn’t hypothetical. HOA-related foreclosures are running nearly 40% above where they stood two years ago, according to ATTOM, as associations move to liens and attorneys more quickly to protect their own cash flow. Associations are actually being pushed into more aggressive collections to avoid financial collapse of their own.
There’s also a timing reality that has nothing to do with policy. Past-due balances are still 70 to 80% recoverable at the 90-day mark, but that rate is roughly cut in half by six months and falls to 20 to 30% by a year. An owner who fell behind in January or February is, by June, approaching the steep part of that curve.
How to run the review
Build a proper aging report. Sort every past-due account into standard buckets of 30, 60, 90, and 120-plus days, and compare where you are now to your January numbers. A board sitting at 9% that was at 6% in January is heading somewhere different from one that’s held steady at 9% all year, even though both look the same as a single snapshot. CAI puts a healthy delinquency range at roughly 5 to 8%.
Match every delinquent account to where it sits in your collections process, and document it. A standard ladder moves from a reminder notice, to a late fee after the grace period, to a formal demand letter around 60 to 90 days, to a recorded lien around 90 to 120 days, with attorney referral or foreclosure as a last resort. Mid-year is the time to discover accounts that have quietly stalled, not escalating, not paying, just sitting. And because states have different escalation procedure laws, reviewing after six months gives you flexibility on notice timelines.
Audit your vendor contracts and expenses
Once a vendor contract is signed, it can run on autopilot for years, and for a board with no property manager cross-checking invoices monthly, that’s real exposure. Sometimes rates quietly creep up, service drifts from what’s specified, and insurance certificates sit in a file, expired, without anyone noticing.
Also, in some states, reviewing contracts isn’t discretionary. For instance, Florida law requires HOAs to solicit competitive bids before signing any service contract that exceeds 10% of the association’s total annual budget (5% for condos), calculated on the full contract value. Professional-service contracts (attorneys, accountants, engineers, architects) are exempt, so the rule lands hardest on the recurring contracts that make up most of a typical budget: landscaping, pool maintenance, janitorial, and security.
Research shows roughly 69% of vendor agreements include auto-renewal clauses with cancellation windows of just 30 to 90 days. Reviewing the contracts mid-year allows you to cancel the agreement within the agreed-upon windows, without the vendor ruining your entire year’s service.
Then there’s the issue of invoice errors. In fact, roughly 39% of vendor invoices contain some kind of error, and duplicate or erroneous payments account for 1 to 2% of total disbursements. And because most of these invoicing and billing errors don’t occur on a day, but start to slip in after some time, reviewing these expenses mid-year is the best time to catch them early, just after they have started.
How to run the audit
Build or refresh a master vendor and contract log with the start date, end date, renewal terms, and cancellation window for every active relationship, including the small recurring items nobody remembers signing. Bids and contracts are official records kept for a set period.
Reconcile six months of invoices against the contracted rates and billing frequency. That way, you’ll catch the hidden incorrect amounts and duplicate charges. After all, a documented billing history is far stronger going into a renewal negotiation than working from memory. Verify that every vendor’s insurance and licensing are actually current. Also, flag every contract renewing in the next six months against your state’s bidding threshold.
Get ready for year-end reporting
The first four parts of this check-up produce real numbers: a variance report, a reserve percentage, a delinquency aging list, and reconciled vendor invoices. This last piece organizes those numbers into something a CPA, an auditor, and every homeowner will actually read, and mid-year is the last comfortable window to start.
Federal tax returns for most associations are due the 15th day of month 4 after the fiscal year ends, which is April 15 for calendar-year communities. Most qualifying associations file the simplified Form 1120-H rather than the standard Form 1120, but that election isn’t automatic: at least 85% of units must be residential, and at least 60% of gross income must come from dues, fees, and assessments. If your community added rental units or commercial tenants this year, those ratios may have shifted, and it’s some of the things worth confirming mid-year rather than at the deadline.
State reporting adds another layer: depending on total revenue, state law requires an escalating level of financial reporting, from a cash receipts summary up through a full audit, and your governing documents may set a stricter standard than the statute. For example, California requires a CPA-prepared review once gross income exceeds $75,000 annually, delivered within 120 days of the fiscal year-end.
Florida moves from compilation to review to full audit at $150,000 and $300,000 in revenue, with a full audit required above $500,000, and statements owed to every owner within 90 days, regardless of tier. Also, the state law prohibits reporting at a lower level than the previous year, even if revenue dropped.
Remember that CPA and audit firms don’t have open calendars waiting for HOAs in January. Audit season runs on roughly the same schedule as tax season, heaviest in the first four months of the year, and firms that plan for capacity staff up four to six months ahead. Engaging one this quarter, while their calendar has room, gets your association good attention instead of a rushed January intake.
Also, clean financials affect something boards rarely connect to reporting readiness: a homeowner’s ability to sell or refinance. Nearly every conventional mortgage in your community requires the association to complete a lender questionnaire, Fannie Mae’s Form 1076 or Freddie Mac’s equivalent, and lenders most commonly kick it back because the numbers don’t match the association’s current books. When that happens, it’s your neighbor’s closing that gets delayed.
How to do it
Re-test your Form 1120-H eligibility if non-member income increased this year. Call your CPA or audit firm this quarter and get an engagement letter signed before their calendar fills. Organize your variance report, reserve reconciliation, delinquency aging, and vendor file into one packet while the details are fresh, and work backward from your distribution deadline, 90 or 120 days after fiscal year-end.
How to automate mid-year financial check-up
Everything covered here, budget, reserves, delinquencies, vendor contracts, year-end prep, gets assembled by hand: someone pulls a bank statement, cross-references a spreadsheet, and tracks down a paper invoice. As you can tell, that’s slow and takes some kind of financial management or accounting knowledge.
Automating the process doesn’t replace the board’s judgment, but it changes the process of assembling the pieces your board needs to make that judgment. For example, with an automated HOA management software, the budget-to-actual variances become a number the board can check anytime instead of a manual reconstruction every six months.
Reserve contributions get tracked against the funding plan in real time. And when the automation platform handles collections through autopay, delinquencies reduce. In fact, research shows that delinquency rates drop from as high as 17% to as low as 6% when you switch from manual collection methods like paper checks to autopay.
Final thoughts
Work through the budget-to-actual report, reserves, delinquencies, and vendor file in whatever order fits your community, and document what you find as you go. That documentation is what protects your board if a decision gets questioned later, and the runway you still have right now is the one advantage a mid-year check-up gives you that a year-end scramble never will. But none of the above steps should turn your board into accountants. Just get a good management platform. Since all the data will be living inside the system, and the system already understands how community association reports run, assembling these reports only takes a few clicks.